

The group chief executive’s ‘vision’ to become ‘the biggest specialty player in the market’ is in response to ‘a huge shift in customers’ demand’ for these types of products – with Beazley deal signifying the cherry on top of Greco’s ambitions
On 1 October 2026, Zurich confirmed that its £8bn acquisition of London-based cyber specialist underwriter Beazley had completed, opening the door for the Swiss insurer to properly establish itself in London and the Lloyd’s market, with new syndicates and product lines now at its fingertips.
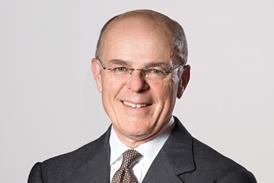
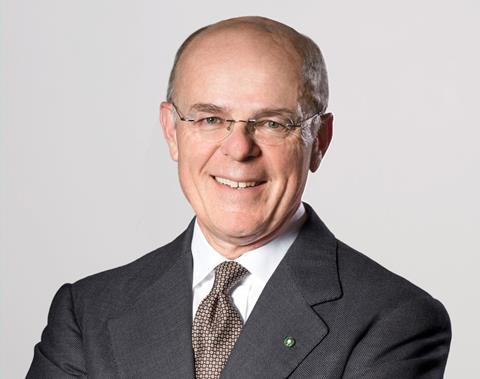
Zurich’s group chief executive, Italian Mario Greco – who has been in post since March 2016 – is certainly rolling up his sleeves to embrace the job at hand, telling Insurance Times that the transaction is not a traditional acquisition of shoring up similar skill sets. Instead, Zurich is “building something that doesn’t exist” to chase down $1bn (£740m) in excess additional revenue by 2029.
In an exclusive conversation with Insurance Times, Greco says: “This is not an integration in the usual way because it’s about building something that doesn’t exist – and so it requires collaboration. It requires engagement in building that and the real opportunity of this integration is to chase revenue growth.
“This is what really makes it interesting for [Beazley] and also rewarding for us. If we can achieve the $1bn of excess additional revenue, that will justify everything. It will be interesting for the Beazley people because they can sell more and [sell] more easily their products and it will be fully rewarding for us too.”
According to Greco, the product overlap between Zurich’s $10bn (£7.46bn) revenue specialty book and Beazley is a “very limited and tiny” 5%, presenting the businesses with the opportunity to “practically fill all the needs of the customers”.
Furthermore, there are some lines of business where both Beazley and Zurich have a smaller offering – which, now combined, provides more clout to drive revenue growth.
“Marine, aviation, political risk – these [are areas] of business that Zurich has no experience on and we were not practising that,” Greco continues. “Of course, there is cyber, where Beazley is much more experienced than Zurich has ever been.
“Then there are other areas where we combine forces, like M&A [and] transactional liability business, where neither of the two is a giant, but by combining forces, we become relevant players and we have a significant market share.
“We have an agreement that for next year, we will never bid against each other and so we will maintain Beazley or Zurich portfolios. We will try to grow more, but we will not bid against each other. And then Beazley and Zurich are free to present new offers to customers.”
One of the most attractive assets Beazley has brought to the Zurich table, however, is seven syndicates at Lloyd’s of London – 2623, 623, 3622, 3623, 5623, 6107 and 4321. Greco confirms that Zurich has now completely scrapped any plans to establish its own syndicates “because it wouldn’t make any sense” considering Beazley’s stronghold here.
Setting targets and shooting for the stars
At the time of interview, just a few short weeks had passed since the ink had dried on the insurer’s acquisition completion paperwork – meaning that Greco is guarded and non-committal about combined targets, metrics and strategies for the near term, especially around what the insurer wants to achieve in Lloyd’s.
Read: ‘It’s not about robots’ – Zurich says technology should remove friction, not judgement
Read: Zurich promotes for new UK CUO
Explore more insurer related content here, or discover more news here
“We need time,” he urges. “We have a date already set in October 2027, [when] we will have our investor day, and definitely by that time we will be ready to present integrated targets with Beazley and plans [for] Lloyd’s, Beazley [and] all aspects of our business.”
This does not mean that Zurich is entirely without direction post-acquisition, however.
Greco points to the Rule 2.7 announcement that Zurich published in March 2026 in alignment with the UK’s City Code on Takeovers and Mergers – this requires an offeror to issue a firm and binding public statement that makes an offer for a UK public company or other code regulated entity.
Within Zurich’s Rule 2.7 announcement, the insurer set out three initial ambitions around its purchase of Beazley that Greco is using as his North Star.
These are that Zurich will “unlock material incremental revenue growth opportunities estimated to be in excess of $1bn (£740m) per annum in the medium term”, achieve “$150m (£112m) of combined annual pre-tax run-rate cost savings” and generate “meaningful capital synergies with a current estimation of $1bn (£74m) of one-off capital extraction”. The firm predicts it will accomplish these goals by 2029.
As to how Zurich plans to implement its outlined cost savings, in particular, the Rule 2.7 document highlighted tactics such as “reduced spend on Zurich’s planned organic specialty build out, reduction in procurement and outsourcing expenses due to greater negotiation power given scale, rationalisation of non-personnel spend, some limited reduction in roles across support functions on both sides [and] real estate optimisation and governance synergies”.
It additionally ringfenced “one-off restructuring and integration costs of approximately $300m (£224m)”.
Greco tells Insurance Times: “We will do work to confirm [and] revise these numbers in the next weeks. We have an investor day in [a few weeks’ time] where we will definitely give an update on [these metrics and the levers we will pull to reach them].
“We have a track record that in the past 10 years, we have never missed one target. None of our targets have been low hanging fruits. We’ve been constantly raising targets in the last 10 years and always delivering on the targets.”
Following ‘high demand’
Looking back to the origins of Zurich’s play for Beazley, Greco says that around 10 years ago, he started to explore which business segments could be ringfenced as “sustainable” growth areas for the insurer.
And while specialty insurance was not initially on Greco’s radar, he tells Insurance Times that this class has “developed itself as the highest growth area in the insurance market” over the last four to five years “because it addresses the needs of customers, governments and societies” – meaning there is “very high customer demand”.
He says: “It’s about construction, infrastructures, defence. It’s about cyber. It’s about energy. It’s about transportation. It’s about financial lines – all the things that are very much in high demand these days.”
Greco acknowledges, however, that the growth of specialty insurance has been heavily influenced by macroeconomic conditions and global trends, creating a very precise moment in time now for the insurer to really lock in and achieve revenue benefits from serving specialty clientele.
“Years ago, nobody cared for cyber,” he continues. “If you go back 10 years, [interest in] cyber [insurance] was very limited because the world was not connected. If you think about data centre development, which is part of specialty [insurance], that comes out of artificial intelligence and technological development. Again, that wasn’t really visible 10 years ago, but now it’s incredibly high demand.
“On the other side, motor is shrinking because people buy less cars and this will continue over time. We will all use less cars because, in the big cities, it’s difficult to park or move with a car.
“This is a huge shift in customers’ demand. The rest of the market is not growing as the specialty one is and [specialty insurance] where customers’ demand is going.
Read: Beazley chief executive to depart after Zurich acquisition
Read: Zurich takes ownership of Beazley as court signs off deal
Explore more insurer related content here, or discover more news here
“The rest of the portfolio, we’re just shrinking it or we are very careful because the market is soft and the opportunities are much less interesting than what we find in specialties and mid-market.”
A ‘consistent and stubborn’ ambition
Greco admits that he has been “very consistent and stubborn” with regards to “implementing this vision” of being “the biggest specialty player in the market” – with this year’s Beazley acquisition being the cherry that sits atop a carefully crafted cake, one that has been in the making for a decade.
He says: “I’ve been following a vision that I had many years ago to grow the specialty [business] and to create the biggest specialty player in the market. We’ve been very consistent and stubborn in implementing this vision and the Beazley acquisition came at the end of it.
“[Now,] 10 years after having more than $10bn [in specialty] business and having already established ourselves as a credible specialty player, the acquisition of Beazley makes perfect sense.
“It is exciting today to be the biggest specialty carrier worldwide. It’s an exciting time and it’s the right place in the market because this is where the growth is.”
Since joining Insurance Times, Katie has successfully obtained a number of industry accolades. At trade body Biba's 2025 Journalist and Media Awards, for example, Katie was named the overall winner and received the Journalist of the Year trophy, alongside the Best Thought Leadership Award for her briefing article on reproductive health MGA Juniper and how insurance can be used to positively impact taboo subjects.View full Profile



No comments yet